Share
The Debrief
Trump’s Tariffs Change Everything
President Donald Trump announced an unprecedented wave of tariffs on April 2, imposing duties as high as 54 percent on fashion imports from key manufacturing countries, including China and Vietnam, and 20 percent on goods from the EU. These measures immediately sparked panic across global markets, ratcheting up the odds of a US recession and causing sharp stock price declines for major fashion brands such as Nike, Victoria's Secret and VF Corp.
Sustainability correspondent Sarah Kent and luxury correspondent Simone Stern Carbone join executive editor Brian Baskin and senior correspondent Sheena Butler-Young to break down the tariffs’ effects on manufacturing, luxury brands, consumer behaviour and potential future shifts within the industry.
Key Insights:
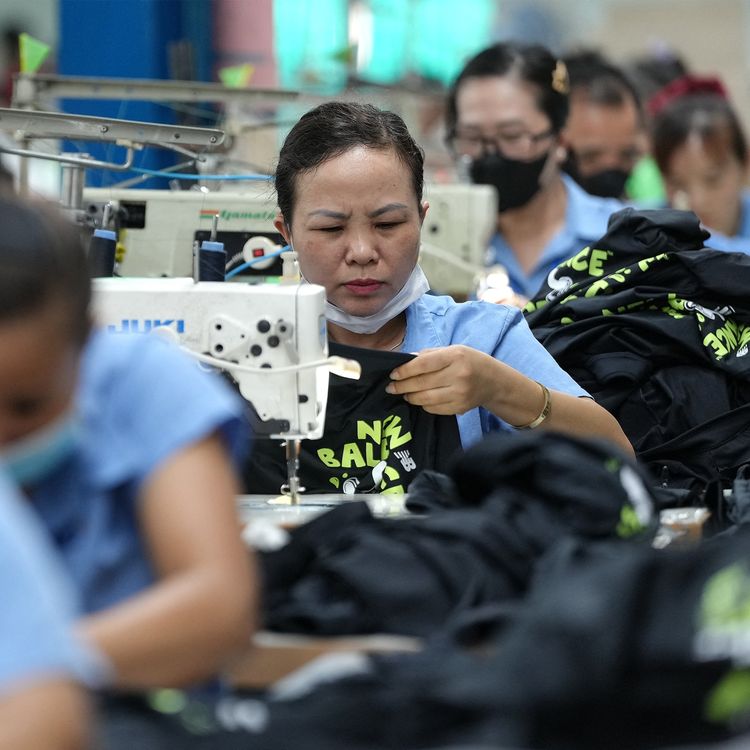
- The belief that these tariffs could quickly restore US-based fashion manufacturing is unrealistic. "It would take years of investment to build up the infrastructure and skill base within the US to replace manufacturing capacity that has been moving abroad for decades. For the apparel industry, it just does not exist on the scale that would be needed," explains Kent.
- Luxury brands, traditionally insulated by European-based production, will also face pressure. "Even for luxury brands that pride themselves for their production in countries like mostly France and Italy, they are going to be hit with some tariffs too," Stern Carbone points out.
- The tariffs introduce a complex challenge for luxury brands, requiring careful balancing of price adjustments, consumer sentiment and creativity amid ongoing economic uncertainty. "It's this mix between pricing, demand, maybe a lack of creativity, and also incentivising customers to actually purchase luxury goods," says Stern Carbone. "You don't know what [Trump] is going to do next, you don't know if this is going to stick, so are you going to spend $10,000 on a handbag - even if you can technically afford it - when you don't know what tomorrow brings?" emphasises Kent.
- The industry isn’t entirely powerless. "Brands have a voice. Brands are part of the global economy. Brands can lobby," says Kent. "They can make it known that they don't like this. If you're not raising your voice and saying, 'hey, this is really hurting big business and it's not making America great again,' then you're not even trying."
Additional Resources:
- Trump’s Tariffs Rock Fashion’s Supply Chain | BoF
- Explainer: How Trump’s Tariffs Threaten Luxury Fashion | BoF
- Op-Ed | Fashion’s Reset: What Tariffs Are Forcing Us to Finally Fix | BoF
- Executive Memo | An Action Plan for Navigating Trump’s Tariffs
More episodes
View all episodes
The Verdict on Luxury Fashion’s Designer Reset
36:52|Fashion's biggest wave of creative-director musical chairs is now a year or so in, and the early read is starting to emerge. Over a dozen major houses have brought in new leadership, and while the broader luxury market is still sluggish, the areas designers can actually move — product, image, storytelling — are showing real signs of life. On a global scale, Chanel is seeing an immediate commercial payoff under Matthieu Blazy, Gucci looks to be stabilising under Demna, and at Dior, Jonathan Anderson's vision is starting to take shape.In this episode, senior correspondent Sheena Butler-Young is joined by BoF's Chief Luxury Correspondent Robert Williams, who has spent the last few weeks on the ground in Milan and Paris covering the shows. Williams runs through the designer reboots at Chanel, Gucci, Dior, Celine, Loewe, Givenchy, Balenciaga and Saint Laurent — and separates the resets that are paying off from the ones still searching for a formula.Key Insights: Williams calls Chanel's revamp under Matthieu Blazy the standout of the cycle, with sales up around 16 percent in the first half of the year. "It's very easy to understand, to digest. It's very visually him, it's very Chanel," he says. The house’s next challenge, Williams says, is balancing the consistency Blazy has established with newness and innovation: :"There needs to be some kind of a formula... at the same time, they need to always make sure they're investing in having new ideas."After a polarizing debut in February, Demna's September show for Gucci clicked. "He was able to bring what he's really good at, which is documenting the way people dress in real life," Williams says, though he's candid that the product left a bit more to be desired: "I'm not sure that the product has caught up with the vision... the collection still has a little bit of a ways to go."At Dior, Jonathan Anderson has sharpened the brand's image quickly, but the clothes are proving trickier to land. Where previous collections felt overcomplicated to some, he sees progress this season: "It felt more cohesive to me and it felt refreshingly just pretty."At Celine, Michael Rider has taken a more evolutionary approach to the house after Hedi Slimane. Williams says Rider has brought “something looser, more playful … a bit more of a focus on design.” Loewe’s JackMcCollough and Lazaro Hernandez, meanwhile, also resisted a wholesale reinvention after Jonathan Anderson: “They've managed to keep the brand pillars going, but rather than the focus being so much about innovation and intellect, they've moved it to the body, to the senses,” Williams says.At Balenciaga, as reports mount that Pierpaolo Piccioli could already be on the way out, Williams argues the house got its strategy inverted: "They kept a lot of the merchandising plan, but they changed the message, the values."At Saint Laurent, with Anthony Vaccarello reportedly exiting after nearly a decade of laser-focused vision, Williams calls it one of the most compelling stories to watch: As luxury fashion became obsessed with relatability and lifestyle, “Vaccarello was running in the opposite direction" The opportunity, and the risk, lies in broadening that identity: "How to build on that without upsetting the apple cart is going to be really risky but also hugely interesting to watch."Additional Resources:Fashion’s Designer Reset (Kind of) Worked | BoFLuxury’s Mid-Year Review | BoFHas Demna Solved Gucci’s Identity Crisis? | BoF
Luxury’s Italian Supply Chain Reckoning Isn’t Over
26:40|In 2024, Milan prosecutors uncovered sweatshop-like conditions within the Italian supply chains of major luxury brands, revealing that workers faced degrading living conditions, low pay, and 15-hour workdays. Nearly two years later, despite brands strengthening internal controls, increasing audits, and restricting subcontracting, labour groups report little fundamental change on the ground.This week, BoF’s Sarah Kent and Sheena Butler-Young explore whether the luxury sector's response has addressed the root causes of this exploitation, or merely added layers of compliance to the same flawed business model.Key Insights:Luxury’s supply chain problems are structural, not isolated. The 2024 investigations exposed more than a handful of bad factories. Kent says exploitative suppliers had become an “open secret” within parts of Italy’s manufacturing ecosystem, enabled by a fragmented supply chain and commercial pressure for low prices, speed and flexibility. “Everyone knows, no one tells because it is convenient to have them exist,” says Kent. “At its heart, when you really press people, they say it’s because of the price brands are willing to pay for products and the speed and flexibility at which they want them produced.”Brands have tightened oversight but audits are creating new pressure on suppliers. Luxury companies have increased inspections, consolidated suppliers and restricted subcontracting. But because each brand often uses a different audit system, manufacturers can face overlapping checks and conflicting requirements at a time when margins are already under pressure. “It’s a time cost, a financial cost, and a big burden to have this quite diversified system of audits that’s hitting suppliers at the moment,” Kent says.Despite tighter controls, there is little evidence that conditions have meaningfully improved for workers. According to Kent, labour groups report little change on the ground, while the luxury slowdown and falling orders are adding more pressure to manufacturers. “ From what I understand from labour groups, there is not a sense that a huge amount has changed on the ground, and I think that's partly because it's quite a complex situation that isn't only linked to luxury supply chains,” Kent says. Without changes to commercial practices that shape working conditions, improvements could remain limited.Compliance alone cannot fix the economics that helped create the problem. For years, luxury positioned craftsmanship, quality and responsible production as part of what justified premium prices. The investigations exposed significant blind spots in that narrative, particularly where brands knew which factories were producing their goods but focused on product quality rather than labour conditions. “It is very interesting to me that for luxury in particular, which has long spoken about issues of labour abuse or environmental degradation as being a fast fashion issue, to have such apparent blind spots when it comes to its own supply chain,” Kent says.Industry-wide solutions remain limited by fragmented standards and voluntary participation. Efforts such as the Milan Protocol aim to create common standards and a database of vetted suppliers. But participation remains voluntary and limited geographically, while brands have struggled to align around a single auditing framework. Kent questions: “If everyone’s not on it, and everyone’s not using it, and they don’t have to be on it and they don’t have to use it, how useful is it?”Additional Resources:Has Fashion Fixed Its Italian Supply Chain Problems? | BoF Inside Luxury’s Italian Sweatshops Problem | BoF Is Luxury Finally Set for a Sustainability Reckoning? | BoF
Fashion’s Latest Obsession: The Grocery Store
22:41|Fashion brands have long used cafes, restaurants and hospitality to sell a broader lifestyle. Increasingly, they’re looking to a less obvious partner: the gourmet grocery store. From branded smoothies and limited-edition tote bags to run clubs, labels are tapping destinations such as Erewhon, Happier Grocery and Meadow Lane to reach consumers in the course of their everyday routines. The draw is clear: these spaces sit at the intersection of food, wellness and community, while offering a highly-sensory environment for brand storytelling. But as more labels pile in, the challenge is making sure these collaborations amount to more than an expensive Instagram moment.In this episode, senior correspondent Sheena Butler-Young is joined by BoF marketing correspondent Haley Crawford to discuss why fashion is moving into the grocery aisle and what brands need to do to get it right.Key Insights: Tie-ups between gourmet grocers and beauty predate today's boom. Erewhon laid the groundwork with early influencer- and celebrity-driven partnerships — including Hailey Bieber's strawberry glazed smoothie in 2022 — while British handbag label Anya Hindmarch has made custom grocery totes for Waitrose and Daylesford for years. Now, Crawford says, "gourmet grocery has just grown so much that there's a much larger sandbox for brands to play in."Crawford is skeptical that grocers are fertile ground for genuinely new fashion products. The more successful tie-ups — like On's long-term Erewhon partnership, which paired a running shoe capsule with a run club and a co-branded recovery juice — use the grocer to market products the brand already has. "This is where brands might have more success than trying to force a raffia skirt that has nothing to do with the brand or the grocer," she says. "It really has to lend itself well to the universe of the grocery store."For most brands, Crawford says the value of these collabs is primarily top-of-funnel – offering marketers a path to connect with customers who may not be ready for a major fashion purchase If they're not ready to shell out $500 for a handbag, they can definitely afford a $15 smoothie," she explains. "That can be something of a revenue driver, but it more so gets them into the funnel and drives that loyalty and brand awareness."In many cases, brands are borrowing "wellness halo" from these stores, Crawford says. But she warns the format risks becoming generic as more brands pile in: "We've seen it with every brand launching their own café... brands need to be wary of that as they tread into the space so it doesn't just become another hot new trend that they're jumping on."The strongest partnerships hinge on genuine identity overlap and understanding a grocer's specific capabilities — whether that's Meadow Lane's ability to whip up custom menu items like a trout dip for Dairy Boy, or Happier Grocery's built-in cafe setup, which let fashion brand Nanushka import its own cafe concept to New York. Prada Beauty took a different route entirely, partnering with local design agencies to stage market takeovers in cities like Milan for its Prada Spring Market. . Crawford's takeaway: brands should ask "what can these grocers offer to me?" before chasing the trend.Additional Resources:How Hotels Became Fashion's Most In-Demand Partner | BoFErewhon Is Coming to New York With a Smoothie Bar | BoF
Can Fashion Sell a New Generation on Trade Jobs?
28:48|Behind every luxury handbag, bespoke suit and couture gown lies an intricate value chain powered by skilled artisans. But as master craftspeople retire without successors, fashion faces a growing shortage of skilled workers — US tailoring employment has fallen roughly 30 percent over the last decade. Nordstrom, North America's largest employer of tailors, is funding tailoring programmes at FIT and Seattle Central College with another planned at ASU FIDM. The effort is aimed at rebuilding that pipeline at a moment when skilled trades more broadly are enjoying renewed interest from young people questioning the value of a four-year degree.In this episode, Sheena Butler-Young is joined by BoF Commercial Features Editor Dan Hastings to explore why fashion’s skilled-trades pipeline has thinned, what the industry is doing to rebuild it, and whether rising tuition costs and anxiety around AI have created a new opportunity to sell young people on these careers. Key Insights:As Hastings sees it, today’s shortage reflects decades of consolidation and the shift of more luxury manufacturing outside traditional fashion capitals. In his view, the industry failed to invest enough in training the next generation of skilled craftspeople, leaving many expert artisans nearing retirement with too few successors in the pipeline. The industry, he says, "kept the offices in the West... but we didn't really train that next generation of handicraft people.”Fashion has long heralded the creative director while overlooking the production side. Hastings argues the industry " venerates the creative director" as its "rock stars," while the people making the clothes remain invisible — a visibility gap that can be compounded, particularly in more junior roles, by pay that doesn’t always reflect the skill required.Apprenticeship programmes tend to cluster around established luxury hubs, leaving many young people unaware these careers are even an option. Hastings argues that interest is there when people know where to look: “It all comes down to knowing that these programmes exist.” But information about apprenticeships, scholarships and bursaries doesn’t always reach prospective workers.Short courses can make trade careers look deceptively fast to enter, but true mastery takes decades. Hastings notes that at some fashion houses, reaching the highest levels can require decades of experience, warning that for a generation “raised on instant gratification,” the long runway between entering the trade and reaching real earning power can be a tough sell.While AI may automate some patternmaking functions, Hastings insists it can't touch the artistry of haute couture. He recalls the tradition of embroidering a strand of hair into a Chanel wedding gown for good luck — “that kind of magic doesn't really happen with AI” — arguing luxury houses will have no choice but to keep investing in training if they want to justify their prices on craftsmanship.Additional Resources:Can AI Ignite a New Generation of Fashion Tradespeople? | BoFFashion's Craftsmanship Challenge | BoFFacing a Shortage of Luxury Artisans, LVMH Seeks Apprentices in the US | BoF
Has Fashion Had Enough of AI?
18:36|For many shoppers, fashion is now experienced primarily through a screen — discovered on social media, watched on runway livestreams and purchased from a product photo. Fashion critic Eugene Rabkin argues in his new book that this shift has left the industry prioritising a garment's image over the garment itself, hollowing out creativity and quality along the way. At the same time, as AI generated imagery floods the feed, a counter-movement is emerging: luxury brands are commissioning painters and illustrators, hosting phone-free dinners and building hands-on experiences designed to pull customers back into the physical world.In this episode, senior correspondent Sheena Butler-Young is joined by Diana Pearl, BoF's US Editor, and Marc Bain, BoF's UK Editor and technology correspondent, to discuss whether this renewed emphasis on human creativity and craft is a meaningful response to fashion's image-first culture — or just the next trend cycle.Key Insights:As consumers increasingly interact with clothing through small screens rather than in person, Bain explains that subtler markers of quality have lost their power to communicate value. "As we interact more with clothing through imagery rather than the physical garments themselves, the logo becomes more important... Now the logo is just the easiest thing to identify. And that has become the most important thing on a garment."Drawing on a concept borrowed from French theory, Bain says the gap between a product's online image and its physical reality has left some shoppers disillusioned — a dynamic he says extends well beyond fast fashion. "It doesn't just apply to Shein..Eugene Rabkin's argument is that it's come to apply to a whole lot of fashion, including luxury fashion... There's been this decline in quality over the years."Bain says and Rabkin are careful not to cast technology as the villain, noting that AI's impact depends entirely on how brands choose to use it. " Technology is amoral. It's a tool..And it's really how it's used that is more important."Pearl points to a wave of luxury brands hiring painters, illustrators and sculptors as a direct response to overly polished, perfected imagery that technology has made ubiquitous — a trend only accelerated by AI. e. "Being perfect and having just this picture-perfect imagery is no longer seen as aspirational. It's actually seen as, ‘slop’ … having that human-made art... is what feels now aspirational and special."As brands pull back from influencer-driven content blitzes in favour of intimate, phone-free events, Pearl says the playbook for measuring success has changed. . "It's all representative of this bigger shift that we're seeing away from volume and just get as much content as possible... towards the depth of connection."Additional Resources:Is Fashion Stuck in Its Simulation Era? | BoFAs AI Floods the Feed, Fashion Marketers Tap Artists | BoFLogging Off Is the New Luxury. How Can Brands Adapt? | BoF
Who's Winning Beauty's H1 Reckoning
27:24|Beauty has long been one of the industry’s most reliable growth engines — fragrance boomed post-pandemic, prestige beauty held up better than other categories, and value-driven brands like e.l.f. proved that sharp pricing and marketing could keep consumers spending. But a slowdown that began last year and has only become more pronounced since has challenged that thinking.In this episode, senior correspondent Sheena Butler-Young is joined by BoF senior beauty correspondent Daniela Morosini to unpack the first half's earnings across the beauty conglomerates — from Estée Lauder and Shiseido to L'Oréal, Beiersdorf and E.l.f. — and identify what’s still driving growth and what’s stalling, as well as what investors will be watching for next.Key Insights:Selective Spending, Not Shrinking Wallets: Consumers haven't stopped buying beauty — they've become pickier about where they spend and what they’re purchasing. "People are just getting a little bit more selective," said Morosini. Shopping itself is shifting, too: "Maybe it's not always Sephora and Ulta. Maybe it's TikTok Shop."Skincare Results, Injectables and the Price-Value Equation: Affordable, results-driven skincare brands are outperforming, while medical aesthetics are surging in parallel. Morosini points specifically to "the derm-backed skincare brands or the dermatological brands, the more affordable ones like CeraVe and La Roche-Posay, alongside the growing pull of the lasers and the injectables."Hair's Unexpected Boom: Hair has emerged as one of the biggest bright spots this earnings season, driven equally by innovation and a cultural shift around hair loss. Morosini notes, "hair loss has just become so much more of a hot topic and I think a lot of stigma has been removed," while also crediting brands like K18 and Olaplex that “have increased what we expect hair products to do for us."Estée Lauder's Momentum Question: Lauder posted a 17 percent stock jump on its first results under new leadership, but Morosini cautions the win may be borrowed. "The question is how much has Estée Lauder improved its brand's desirability and how much has it benefited from a rising tide," she says, adding that stripped of Amazon Prime Day effects, US growth was closer to "about two percent."The Danger of the One-Hero Brand: From E.l.f.'s reliance on Rhode to Beiersdorf's dependence on Nivea, this earnings season exposed how a single hero product can mask underlying weakness. "When that's basically all concentrated around one brand, that makes investors a little bit nervous," Morosini says, noting the read-through for M&A: “At a certain point you have to buy the growth."Additional Resources:Beauty Is Growing. Not Everyone’s Benefitting. | BoFCan Estée Lauder Turn a Moment Into Momentum? | BoFBeauty Is Betting on Fragrance. Why Isn’t Shiseido? | BoF
Why Upcycling Is Suddenly Everywhere in Fashion
28:24|For a long time, upcycling sat on the fringes of the fashion industry, a tactic used primarily by small independent designers, niche sustainability labels and in one-off capsule collections. That's changing. At Paris Couture Week this spring, Swiss designer Kevin Germanier closed the season with a collection made entirely from excess inventory across seven LVMH-owned brands. Coach is turning used denim into new bags, and Uniqlo is remaking unsellable and used garments under its RE label.In this episode, senior correspondent Sheena Butler-Young speaks to senior editorial associate Shayeza Walid to explore why upcycling brands are increasingly marketing upcycling through creativity and individuality rather than sustainability alone, and what's really driving the shift from new EU regulations to a changing consumer mindset.Key Insights:Selling Creativity, Not Just Conscience: Walid points to a fundamental shift in how upcycling is marketed. It's no longer framed primarily as an environmental fix, but as a source of design distinction and story. "It felt like the term was becoming ubiquitous across marketing," she says, noting that upcycling has moved from something "relegated to a certain type of consumer or a certain type of brand" to being claimed by some of the industry's biggest names.Regulation Is Quietly Doing the Heavy Lifting: Walid connects the timing of the boom to the EU's ban on the destruction of unsold goods, which came into force in July. She notes that Kevin Germanier's LVMH-backed couture collection was deliberately built from unsold stock, not deadstock fabric — a distinction he emphasised on stage. "It also means that they'll have to figure out sustainable and approved ways for using their excess stock, and upcycling is one of the methods for that."Deadstock vs. Textile Waste — Not the Same Debate: Walid unpacks a live tension among practitioners: using deadstock fabric is being challenged by some critics as not addressing overproduction, since it still puts commercial value on excess production. "With deadstock, it's the same as using new fabric in the sense that they're rolls of fabric... that's not necessarily what upcycling is about," while brands like E.L.V. Denim work directly with used, discarded garments instead.The Infrastructure Is Finally Catching Up: Sorting, collecting and sourcing — the industry's biggest upcycling bottleneck — is improving. Walid cites organisations like Fashion for Good working on AI-assisted sorting, and platforms such as Nona Source and The Materialist connecting brands to deadstock fabric. "There's a greater design interest in it now more than there's ever been," she says of the shift she's tracked through conversations with suppliers.The Consumer Wants Range, Not a Label: Walid argues the audience for upcycled product has broadened well beyond the sustainability shopper. "You could have an upcycled Miu Miu product today, and maybe that says that you like high fashion... but also you think it's cool that your product is from an upcycled material," she says, describing a consumer who wants variety in their closet rather than to be defined by one aesthetic or ethic.Scale Remains the Unsolved Problem: Despite the momentum, there are limits. Sizing and colour inconsistency frustrate wholesale buyers, the process is inherently slower than working with virgin material, and export bans on used textiles in countries like Bangladesh complicate sourcing. She also flags that upcyclers in the Global South — in markets like Kantamanto in Ghana — have done this sort of work for generations but remain largely excluded from the value chain brands are now building.Additional Resources:Why So Many Fashion Brands Are Upcycling | BoFWhy Fashion’s Economics Work Against Sustainable Brands | BoFCan the EU Ban on Destroying Unsold Goods Actually Work? | BoF
The Influencer Follower-Count Era Is Ending
23:25|For years, follower count was the clearest shorthand for a creator's value — more followers meant more reach, more brand deals, more money. But social media doesn't work that way anymore. TikTok's For You page, Instagram's suggested posts and other algorithmically curated feeds mean creators can reach huge audiences without those people ever following them. At the same time, affiliate marketing platforms like LTK and ShopMy are giving brands a much clearer picture of who actually drives sales, with smaller creators often outperforming bigger names. In this episode, senior correspondent Sheena Butler-Young talks to BoF US Editor Diana Pearl about how brands and creators are rethinking the value of an audience, and where creator value is headed next.Key Insights:A huge following no longer guarantees cultural weight. Pearl points to the gap between raw numbers and actual impact: "You look at someone like Dixie D'Amelio, who has almost 54 million followers on TikTok... but I would not say [she is] as culturally relevant as someone like Alex Earle, who has not even 9 million followers on TikTok."New platforms have made it possible to see exactly who is driving sales, not just who has the biggest audience. As Pearl explains, "ShopMy really changed that — they offer brands a lot more insight into which creators are actually driving sales, even if they're not running a paid partnership."TikTok's For You page and Instagram's suggested posts have done more than any other shift to break the link between followers and visibility. "Those are the two primary factors that have really diminished the importance of follower count," she says, "because you can have someone with 300 followers who goes viral."The single most important quality a creator can build today resists easy measurement. "Trust is the number one most important thing that an influencer or creator can curate today," Pearl says, "and that trust is not something that can necessarily be measured by metrics on a spreadsheet."Chasing every viral trend is a losing strategy — consistency is what builds a durable audience. "Playing the long game is really the best strategy," she says. "Staying true to who you are — that's how you build that community. That is how you built that trust in that community."Additional Resources:Why Follower Count Matters Less Than Ever | BoFNot All Creators Convert. Here's How to Find Those That Do. | BoFFrom Hype to Discipline: The New World of Influencer Marketing | Case Study | BoF
What the Best Fashion Stores Get Right
31:31|For much of the last decade, fashion brands and retailers were fixated on making shopping as seamless as possible — endless product online, algorithmic recommendations, next-day delivery. But after years of digital sameness, something more analogue is starting to feel exciting again. That shift sits at the heart of BoF's new retail package, The Best Fashion Stores in the World — an insider's guide to 65 independent retailers spanning from Brooklyn's Ven. Space to Dongliang in Shanghai, Alara in Lagos and Dover Street Market. BoF retail editor Cathaleen Chen joins senior correspondent Sheena Butler-Young to discuss why independent retailers are becoming more important to shoppers, brands and the wider fashion ecosystem, as well as why the ritual of engaging with fashion IRL is more important than ever.Key Insights: Chen says the list's three pillars — curation, experience and partnership — were designed to reflect more than consumer taste. Partnership, she explains, addresses "the support and the responsibilities that all retailers have to the fashion ecosystem," at a moment when department stores have earned a track record for not paying vendors and multi-brand retail has been reshaped by the collapse of players like Matches and the struggles of Net-a-Porter.With e-commerce solving for intent-driven shopping, Chen argues stores now win on discovery. As she puts it: "If you know exactly what you want, you shop online. If you don't know what you want, you shop in stores." She adds that the best shopkeepers add value "not just discovery for new brands" but new ways of styling — an eye that "allows designers to sort of view their collection in new eyes" in a way social feeds may fall short, Per wholesale data from the platform Joor, independent retailers' share of transactions rose from 49 percent in 2020 to 62 percent in 2025 — meaning independents "now make up the majority of transactions in wholesale" on the platform, a significant insight even when accounting for the caveat that it reflects one marketplace.The list includes retailers in Ibiza, Hangzhou, Cairo, Cartagena and Kuwait City — a deliberate move beyond fashion's traditional capitals. Citing a conversation with Kallmeyer founder and chief executive Daniella Kallmeyer, Chen notes that regional boutiques may be " even more important than the larger international stores because they're able to penetrate these outer-tier markets," which represent white space for fashion, rather than lesser opportunity.The appeal of independent retail is fundamentally about a different mindset: casual discovery and "bopping around the neighbourhood," which Chen calls "the opposite of online shopping, where I know exactly what I want.”Asked to name the one quality that will define the best stores for the next decade, Chen didn't hesitate: "I think conviction is what makes these doors so special, and ultimately what makes them so successful today" — pointing to Ikram Goldman's boutique, Ikram, in Chicago, and her famously intimate client relationships as the clearest example.Additional Resources:Why Independent Retail Is More Important Than Ever | BoFThe Best Fashion Stores in the World | BoFThe Debrief | Why Some Retailers are Ignoring the Internet | BoF